Florida Homeowners Insurance vs. Flood Insurance: What’s the Difference?
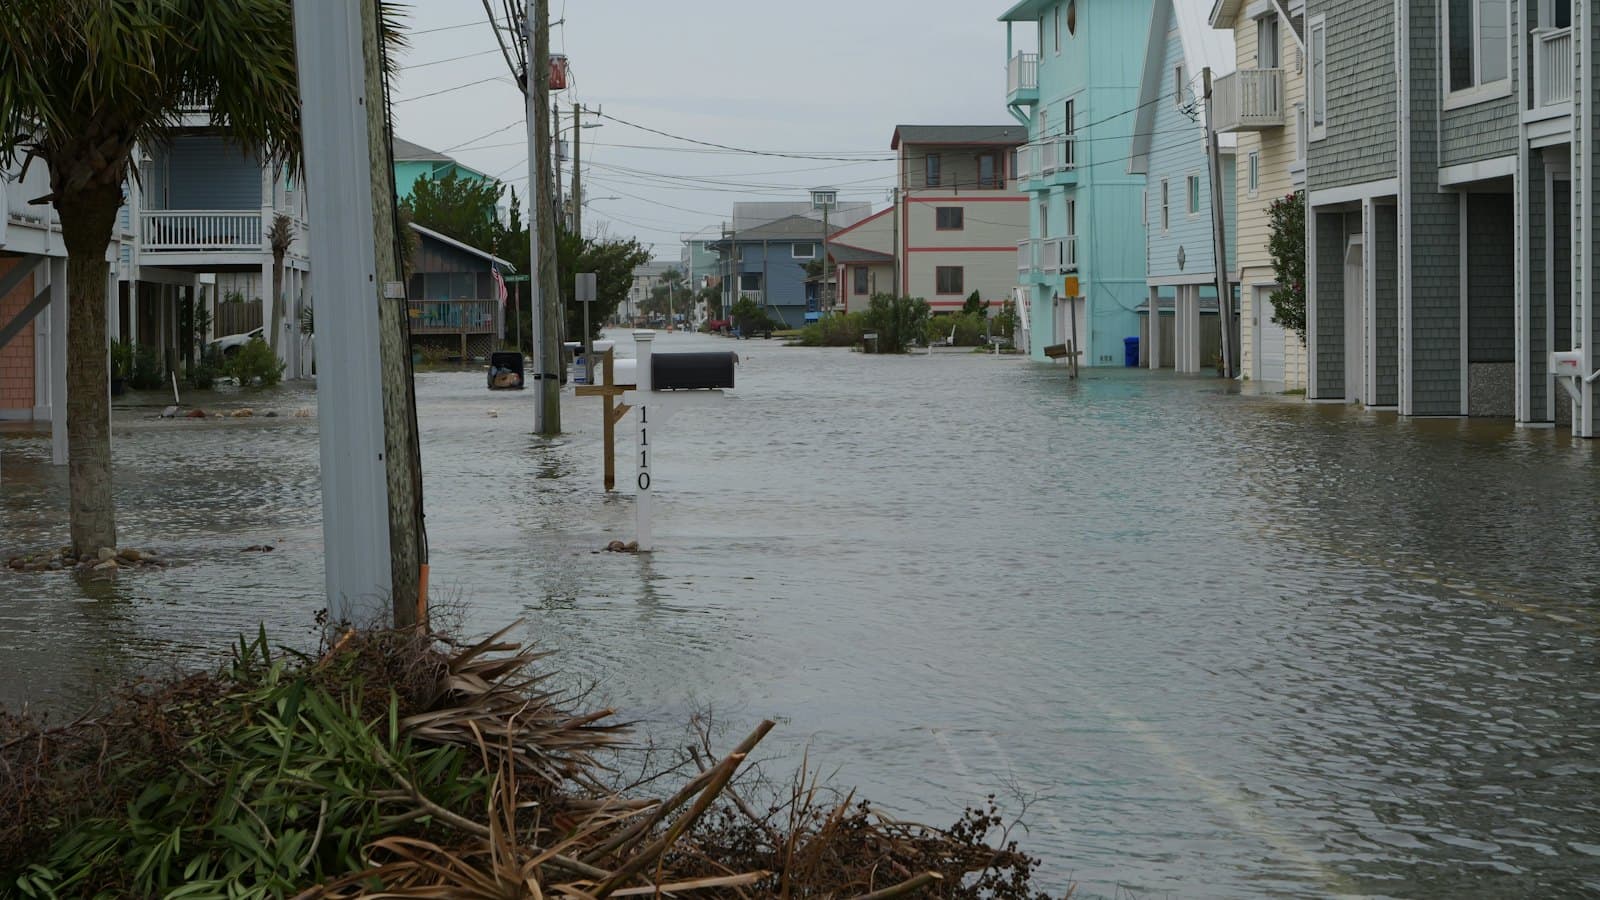
Does your homeowners insurance cover flooding? In most cases, it does not. Florida’s Office of Insurance Regulation encourages homeowners to consider flood insurance because most homeowners policies exclude flood damage.[1]
For Fort Lauderdale and other Florida communities, understanding the difference can help you identify a major coverage gap before a storm.
Homeowners and flood coverage address different losses
A homeowners policy can protect against covered events such as fire, theft, and certain wind or water losses, subject to the contract. Flood insurance addresses qualifying flood losses under its own terms.
Do not assume every kind of water damage is treated the same. A plumbing leak, wind-driven rain, and rising floodwater can involve different policy provisions. The cause of the damage matters.
Review the details of both policies
Ask your agent to help you check:
- Whether flood coverage is included, endorsed, or needs a separate policy.
- What protection applies to the building and your belongings.
- Coverage limits, deductibles, and exclusions.
- Whether your mortgage lender requires particular coverage.
- When a new policy would actually take effect.
An area outside a high-risk flood zone can still experience flooding. Consider the property’s exposure rather than relying only on whether insurance is required by a lender.[2]
Don’t wait until a storm is approaching
National Flood Insurance Program policies generally have a 30-day waiting period, although exceptions apply. Private policy waiting periods can differ. Confirm the effective date before assuming protection is in place.[2]
Review your protection with Newbridge Insurance
Newbridge Insurance can help you review your homeowners policy and available flood coverage options. Bring your current declarations page so we can discuss limits, deductibles, and potential gaps.
Call (954) 357-2715 or visit NewbridgeInsuranceFL.com to request a coverage review. Availability and coverage depend on the insurer and policy terms.